

Conventional Mortgages in Canada: Down Payment, Rates and Requirements
This Page's Content Was Last Updated: September 15, 2026


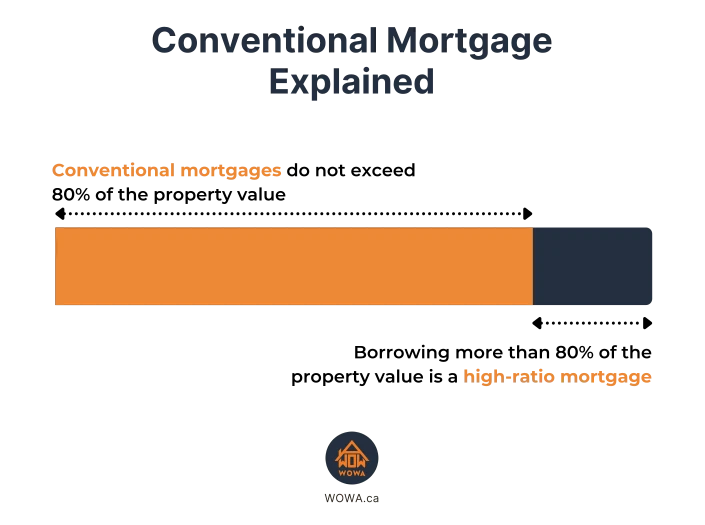
A conventional mortgage in Canada means a mortgage where you make a down payment of 20% or more of the home's purchase price. Because the mortgage is no more than 80% of the property's value, you are not required to pay for mortgage default insurance.
For example, if you buy a $600,000 home with 20% down, you would make a $120,000 down payment and borrow $480,000.
Conventional mortgages can be used for homes of any price, subject to the lender's requirements. They are particularly important for homes priced at $1.5 million or more, since these properties are not eligible for standard high-ratio mortgage default insurance and therefore require at least 20% down.
Conventional Mortgage Rates in Canada
| Term | Insurable Conventional20%+ down, home under $1.5M, 25-year amortization | Uninsurable ConventionalRefinances, homes $1.5M+, 30-year amortizations, rentals |
|---|---|---|
| 1-Year Fixed | 4.59% Innovation Credit Union | 4.94% CIBC |
| 2-Year Fixed | 4.44% 4.59% at 65-80% LTV Frank Mortgage | 4.44% Shinhan Bank |
| 3-Year Fixed | 4.19% Butler Mortgage | 4.19% Butler Mortgage |
| 4-Year Fixed | 4.29% Meridian | 4.44% Shinhan Bank |
| Popular5-Year Fixed | 4.34% Butler Mortgage | 4.34% Butler Mortgage |
| 5-Year Variable | 3.30% 3.50% at 65-80% LTV Butler Mortgage | 3.55% Butler Mortgage |


- A conventional mortgage requires a down payment of at least 20%, resulting in a loan-to-value (LTV) ratio of 80% or less.
- You do not pay a mortgage default insurance premium with a conventional mortgage.
- Homes priced at $1.5 million or more require at least 20% down.
- Conventional mortgage rates are usually higher than insured mortgage rates. However, rates depend on factors such as your LTV, whether the mortgage is insurable, amortization, property type and lender.
- With a 20% or greater down payment, lenders can generally offer 30-year amortizations, although availability and rates depend on the lender.
A conventional mortgage does not have one specific interest rate. Your rate depends on your lender and the details of your mortgage.
Two borrowers with conventional mortgages can be offered different rates even if they have similar credit scores. Important pricing factors include your loan-to-value ratio, mortgage term, fixed or variable rate, amortization, property use and whether the mortgage qualifies for lender-paid mortgage insurance.
For example, a borrower with exactly 20% down may receive different pricing from someone putting 35% down. Similarly, a 30-year mortgage may be priced differently from a comparable 25-year mortgage.
Insured mortgages have lower advertised rates because mortgage default insurance reduces the lender's risk. However, that does not mean an insured mortgage is always cheaper. A borrower with less than 20% down must also account for the cost of the mortgage insurance premium, while conventional mortgage borrowers avoid that cost entirely.
The best comparison is therefore the total cost of borrowing, not just the advertised mortgage rate.
What Is a Conventional Mortgage?
A conventional mortgage has an LTV of 80% or less, meaning your mortgage represents no more than 80% of the home's value.
For a home purchased for $500,000:
| Amount | |
|---|---|
| Home Price | $500,000 |
| 20% Down Payment | $100,000 |
| Conventional Mortgage | $400,000 |
| Loan-to-Value Ratio | 80% |

Mortgage default insurance protects the lender, not the homeowner, against losses if a borrower defaults.
With less than 20% down, eligible borrowers need borrower-paid mortgage default insurance, such as from CMHC, Sagen, or Canada Guaranty. With 20% or more down, you do not need to pay this premium.
Technically, a lender may choose to purchase insurance on some conventional mortgages at its own expense. This is sometimes called lender-paid or portfolio insurance. From a borrower's perspective, however, the important difference is that you are not being charged the high-ratio mortgage insurance premium.
Conventional Mortgage vs. Insured Mortgage
| Conventional Mortgage | High-Ratio/Insured Mortgage | |
|---|---|---|
| Down Payment | 20% or more | Less than 20% |
| LTV | 80% or less | More than 80% |
| Borrower-Paid Default Insurance | Not required | Required |
| Home Price Limit | No standard insured-mortgage price cap; lender limits apply | Home must be below $1.5 million |
| 30-Year Amortization | Often available, depending on lender | Available to qualifying first-time buyers and buyers of new builds |
| Mortgage Rate | Depends on LTV, lender, insurability and other factors | Often competitively priced, but not automatically cheaper overall |
A conventional mortgage is sometimes also called an uninsured mortgage, although the terms are not perfectly interchangeable because a lender may insure a low-ratio mortgage at its own expense.
10% vs. 20% vs. 35% Down Payment
Consider a $600,000 home. The following examples show how your down payment affects the amount you need to borrow.
For simplicity, the payment examples assume a 25-year amortization and a 4.50% mortgage rate in all three scenarios.
| 10% Down | 20% Down | 35% Down | |
|---|---|---|---|
| Home Price | $600,000 | $600,000 | $600,000 |
| Down Payment | $60,000 | $120,000 | $210,000 |
| Mortgage Before Insurance | $540,000 | $480,000 | $390,000 |
| LTV | 90% | 80% | 65% |
| Mortgage Insurance Premium | $16,740 | $0 | $0 |
| Mortgage if Premium Is Financed | $556,740 | $480,000 | $390,000 |
| Approx. Monthly Payment | $3,081 | $2,657 | $2,159 |
| Mortgage Type | Insured | Conventional | Conventional |
At 10% down, the mortgage before insurance is $540,000. At a 90% LTV, a standard CMHC premium rate of 3.10% would result in a $16,740 mortgage insurance premium. If you add that premium to the mortgage rather than paying it upfront, the starting mortgage balance becomes $556,740.
At 20% down, the mortgage becomes conventional and there is no borrower-paid default insurance premium. Increasing the down payment to 35% reduces the mortgage balance even further and may also qualify for more favourable pricing from some lenders.
Applicable provincial sales tax on mortgage insurance premiums, where required, is not included in this example.
Is Putting 20% Down Always Better?
Putting down 20% has an obvious advantage: you avoid the borrower-paid mortgage insurance premium and begin with more equity in your home.
However, using more of your savings for the down payment also means having less cash available for closing costs, renovations, emergencies or investments.
There can also be differences in mortgage rates. An insured mortgage with less than 20% down may sometimes receive a lower rate than a conventional mortgage with exactly 20% down. Meanwhile, some lenders offer better conventional rates at lower LTV levels, such as when you put 35% or more down.
For that reason, compare the down payment, mortgage insurance premium, interest rate, monthly payment and total borrowing cost rather than choosing based on the mortgage rate alone.
Buying a Home for $1.5 Million or More
Homes priced at $1.5 million or more cannot use standard high-ratio mortgage insurance. This means you need a down payment of at least 20%.
For example:
- A $1,500,000 home requires a minimum down payment of $300,000.
- A $1,750,000 home requires a minimum down payment of $350,000.
- A $2,000,000 home requires a minimum down payment of $400,000.
Your lender may require more than 20% depending on your income, credit profile, the property and its location.
This rule is different for properties priced below $1.5 million. Below that threshold, an eligible owner-occupied home may be purchased with less than 20% down, with the minimum down payment calculated as 5% of the first $500,000 and 10% of the portion above $500,000.
25-Year vs. 30-Year Conventional Mortgage
One advantage of making a conventional down payment is greater flexibility over amortization.
When your down payment is 20% or more, your lender determines the maximum amortization it is willing to offer. Many lenders offer conventional mortgages with amortizations of up to 30 years.
A 30-year amortization reduces your required monthly mortgage payment because the loan is repaid over a longer period. The trade-off is that you accumulate equity more slowly and pay more interest.
Consider a $600,000 home with 20% down, leaving a $480,000 conventional mortgage. If the rate were 4.50% for the entire amortization:
| 25-Year Amortization | 30-Year Amortization | |
|---|---|---|
| Mortgage Amount | $480,000 | $480,000 |
| Interest Rate | 4.50% | 4.50% |
| Monthly Payment | $2,657 | $2,420 |
| Total Interest | $317,001 | $391,284 |
| Total Payments | $797,001 | $871,284 |
The 30-year amortization lowers the monthly payment by approximately $237, or about 9%. However, if the 4.50% rate remained unchanged for the entire mortgage, you would pay approximately $74,283 more interest.
In reality, Canadian mortgages are normally renewed several times during their amortization, so your future interest rates will change. These figures are intended to show the effect of extending the amortization while holding everything else constant.
A 30-year mortgage can make monthly mortgage payments easier to manage, while a 25-year mortgage pays down principal faster and reduces long-term interest costs.
Benefits of a Conventional Mortgage
No Borrower-Paid Mortgage Insurance Premium
The biggest immediate benefit is avoiding the mortgage default insurance premium normally required when your down payment is less than 20%.
Depending on the size of the insured mortgage and its LTV, this can save thousands or tens of thousands of dollars.
Smaller Mortgage Balance
A larger down payment means you borrow less from the beginning. This results in lower monthly payments and less interest paid over the life of the mortgage.
More Home Equity
Putting at least 20% down gives you more equity immediately. Greater equity can give you additional financial flexibility later, including the potential ability to borrow against your home through refinancing, a home equity line of credit (HELOC) or another secured borrowing product, subject to lender requirements.
More Amortization Options
Borrowers with conventional mortgages are not subject to the same insured-mortgage amortization restrictions. Your lender may offer a 30-year amortization even if you are not a first-time buyer and are not purchasing a new build.
Ability to Buy More Expensive Homes
A conventional mortgage is required when buying a home for $1.5 million or more because standard high-ratio mortgage insurance is unavailable at that price.
Disadvantages of a Conventional Mortgage
The main drawback is the amount of cash required upfront. Saving a 20% down payment can take considerably longer than saving the minimum down payment required for an insured mortgage.
Putting a large amount of money into your home reduces your liquidity. Before increasing your down payment, consider whether you will still have enough money for closing costs, moving expenses, repairs and an emergency fund.
How to Qualify for a Conventional Mortgage
Making a 20% down payment does not automatically qualify you for a mortgage. Your lender still needs to determine whether you can afford the loan and meet its underwriting requirements.
Down Payment and Closing Costs
You need at least 20% of the purchase price for the down payment. You should also have funds available for closing costs such as land transfer tax, legal fees, title insurance and adjustments.
Your lender will normally ask for documentation showing where your down payment came from, such as bank or investment statements. A gifted down payment may require a gift letter and supporting documentation.
Income and Employment
Your lender may ask for documents such as recent pay stubs, an employment letter, T4 slips and Notices of Assessment.
Self-employed borrowers may need additional documentation, including tax returns, Notices of Assessment and business financial information.
Debt Service Ratios
Lenders compare your housing costs and other debts with your income using measures such as the Gross Debt Service (GDS) and Total Debt Service (TDS) ratios.
Acceptable ratios depend on the lender, your credit profile and the overall strength of your mortgage application.
Mortgage Stress Test
New uninsured mortgages from federally regulated lenders must pass Canada's mortgage stress test.
You generally need to qualify at the greater of:
Your mortgage contract rate + 2 percentage points
or
5.25%
For example, with a mortgage rate of 4.50%, you would generally need to qualify using a rate of 6.50%.
An exception applies to current uninsured mortgage holders switching federally regulated lenders at renewal without increasing their mortgage balance or amortization.
Credit History
There is no single legally required minimum credit score for every conventional mortgage in Canada.
A credit score around 680 or higher is a common benchmark for strong access to prime mortgage products, but lender requirements vary. A lower score does not automatically mean you cannot obtain a conventional mortgage, although you may face fewer lender options, a higher rate or additional requirements.
Property
The lender also evaluates the property securing the mortgage. A home appraisal may be required to confirm the property's value and suitability.
Property type can affect mortgage qualification and rates. Rental properties, unusual properties and homes in remote or less marketable areas may have different lending requirements.
Conventional Mortgage vs. Collateral Mortgage
A conventional mortgage and a collateral mortgage are not opposites.
"Conventional" generally describes the mortgage's LTV and insurance status. "Collateral" describes how the lender registers its security against your property.
This means a mortgage can be both a conventional mortgage and a collateral-charge mortgage at the same time.
A collateral charge may allow a lender to secure additional borrowing against your home without registering another charge, but it can also result in additional legal or administrative steps when switching lenders.
When comparing mortgages, consider both the mortgage's LTV/insurance classification and whether it uses a standard or collateral charge.
Frequently Asked Questions
What is a conventional mortgage in Canada?
A conventional mortgage has a down payment of at least 20%, meaning the mortgage has a loan-to-value (LTV) of 80% or less. Borrower-paid mortgage default insurance is not required.
What is the minimum down payment for a conventional mortgage?
The standard minimum is 20% of the home's purchase price. Your lender may require a larger down payment based on the property or your financial situation.
Are conventional mortgage rates higher than insured mortgage rates?
Usually. Insured mortgages often receive competitive rates because mortgage insurance reduces the lender's risk, but conventional mortgage rates vary significantly based on LTV, insurability, amortization, property type and lender.
Some conventional borrowers, particularly those with lower LTVs, may receive very competitive rates. You should compare the total cost, including any mortgage insurance premium, rather than the interest rate alone.
Can I get a 30-year conventional mortgage?
Yes. With 20% or more down, your lender generally sets the maximum amortization period. Many lenders offer 30-year conventional mortgages.
A 30-year amortization lowers the monthly payment but increases total interest costs compared with a 25-year amortization.
Can I get a conventional mortgage with exactly 20% down?
Yes. A 20% down payment results in an 80% LTV and qualifies the mortgage as conventional.
Do I need CMHC insurance with 20% down?
No. Mortgage default insurance paid by the borrower is typically required when the down payment is below 20%.
Your lender may separately choose to insure an eligible conventional mortgage at its own expense.
Do homes over $1.5 million require a conventional mortgage?
Yes, if the purchase is mortgage-financed. Homes priced at $1.5 million or more are not eligible for standard high-ratio mortgage insurance, so you need at least 20% down.
Does a conventional mortgage require a mortgage stress test?
Borrowers taking out a new uninsured mortgage from a federally regulated lender must pass the stress test at the greater of the contract rate plus 2% or 5.25%.
There is an exception for certain straight switches at renewal where a current uninsured borrower changes lenders without increasing the mortgage amount or amortization.
Can I refinance a conventional mortgage?
Yes. A conventional mortgage can be refinanced subject to the lender's maximum LTV and qualification requirements.
Refinancing may allow you to access home equity, consolidate debt, change your amortization or change mortgage features, but mortgage penalties and other refinancing costs may apply.
Where can I get a conventional mortgage?
Conventional mortgages are widely available from Canadian banks, credit unions, mortgage finance companies and other lenders.
A mortgage broker may also compare conventional mortgage products from multiple lenders.
Do mortgage brokers charge a fee for conventional mortgages?
For many prime conventional mortgages, the lender pays the mortgage broker a commission, so the borrower does not pay a separate brokerage fee.
However, borrower-paid fees can apply in some situations, particularly with alternative or private mortgages, complex financing or lenders that do not compensate the broker. You may also encounter lender, appraisal, legal or administration fees.
Any brokerage fees and compensation should be disclosed before you commit to the mortgage.
Is a conventional mortgage better than an insured mortgage?
Neither option is automatically better.
A conventional mortgage avoids the borrower-paid insurance premium and starts with more home equity, but it requires substantially more money upfront.
An insured mortgage allows you to buy with a smaller down payment and may receive a competitive interest rate, but you must account for the mortgage default insurance premium.
The better option depends on your savings, income, mortgage rate, expected time in the home and what you would otherwise do with the additional down payment funds.
The Bottom Line
A conventional mortgage generally requires at least 20% down and allows you to avoid borrower-paid mortgage default insurance. It can reduce your mortgage balance, increase your starting equity and provide more flexibility over amortization.
However, putting 20% down does not automatically guarantee the lowest mortgage rate or the lowest overall cost. Conventional mortgage pricing depends on your LTV, credit profile, amortization, property, insurability and lender.
When deciding how much to put down, compare the cash required upfront, mortgage insurance premium, interest rate, monthly payment and total borrowing cost. For buyers with enough savings, the right conventional mortgage can provide significant long-term savings without putting too much of their available cash into the home.
Disclaimer:
- Any analysis or commentary reflects the opinions of WOWA.ca analysts and should not be considered financial advice. Please consult a licensed professional before making any decisions.
- The calculators and content on this page are for general information only. WOWA® does not guarantee the accuracy and is not responsible for any consequences of using the calculator.
- Financial institutions and brokerages may compensate us for connecting customers to them through payments for advertisements, clicks, and leads.
- Interest rates are sourced from financial institutions' websites or provided to us directly. Real estate data is sourced from the Canadian Real Estate Association (CREA) and regional boards' websites and documents.