

What is a Certified Cheque
What You Should Know
- A certified cheque is a personal cheque that your financial institution verifies and certifies.
- The financial institution confirms that sufficient funds are available in the account and reserves those funds for the cheque.
- Certified cheques are still available at some Canadian banks and credit unions, but bank drafts are now a more common alternative.
- The person writing the cheque is typically charged a fee, which varies by financial institution and is often $10 to $20.
- A certified cheque or bank draft can still be subject to a deposit hold, particularly if the receiving financial institution needs to verify it.
What is a Certified Cheque?
A certified cheque is a personal cheque that has been verified by the issuing financial institution. The bank or credit union confirms that sufficient funds are available and sets aside the money needed to cover the cheque.
Certified cheques are less common than they once were. Many Canadian banks now make bank drafts more prominent as a way to make large or important payments.

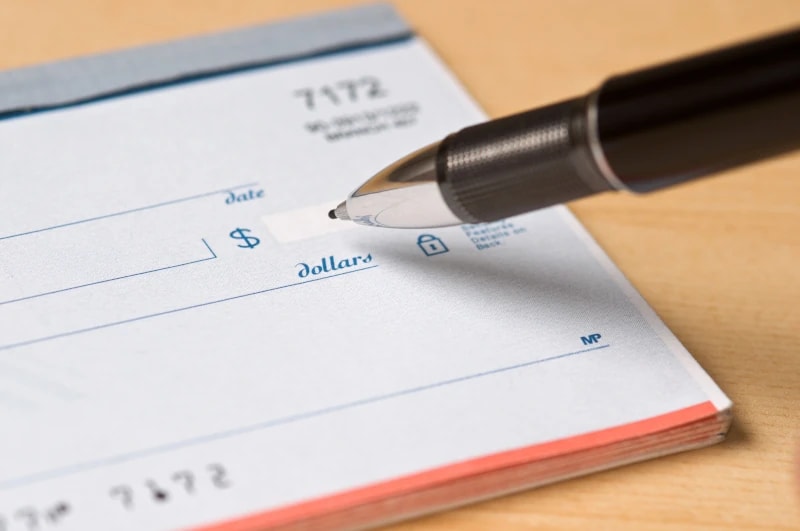
How Does a Certified Cheque Work?
To certify a cheque, the financial institution confirms that the account has sufficient funds and reserves the amount needed to pay the cheque.
Certified cheques look similar to regular personal cheques but have a stamp from the financial institution certifying that the cheque is valid.
Once certified, the account holder cannot use the funds that have been reserved for the cheque. For example, if you have a certified cheque for $10,000 issued, the bank will place a hold on $10,000 from your account and hold it until the cheque recipient cashes the cheque.
Once the cheque is cashed or deposited, the hold is released, and the funds are transferred to the recipient.
Certification provides additional assurance that the funds were available when the cheque was certified. However, receiving banks may still place a hold on the deposited cheque, and counterfeit or altered cheques can still be returned.
How to Get a Certified Cheque
If your financial institution offers certified cheques, you will need to visit a branch with the cheque you want certified. A bank teller will assist you in filling out the necessary information and will verify that you have enough funds in your account for the amount of your cheque. Once the cheque is issued, it will be stamped by the bank, certifying that it is a certified cheque.
Availability and procedures vary by bank. Since bank drafts are more commonly offered, it can be worth asking whether a bank draft would meet the recipient’s requirements instead.
Certified Cheque vs. Bank Draft
The main difference is who creates the payment.
With a certified cheque, you write a personal cheque and your financial institution certifies it after confirming that the funds are available.
With a bank draft, the financial institution withdraws the money from your account and issues the draft itself.
Both can be used for larger transactions where the recipient wants greater assurance than they would get from a regular personal cheque. Bank drafts are generally more commonly offered by Canadian banks today.


Banks charge a fee for issuing certified cheques that typically ranges from $10 to $20 each. There’s usually no extra fee for depositing a certified cheque outside of any transaction fees charged by your chequing account. Some institutions charge a higher fee when certification is requested by someone other than the person who wrote the cheque.




Fees shown are generally for certification requested by the person writing the cheque. Availability and fees can vary by account and financial institution.
Alternatives to Certified Cheques
Bank Drafts
Bank drafts are one of the most common alternatives to certified cheques in Canada.
Instead of certifying a cheque written by the customer, the financial institution withdraws the funds and issues the draft. They offer additional benefits such as faster processing times and lower fees. Some banks, including RBC and CIBC, no longer certify cheques drawn on personal accounts and direct customers to bank drafts instead.
Major Canadian banks commonly charge around $9.95 for a standard bank draft, although fees can vary by account and institution.
Money Orders
Canada Post also offers postal money orders. They currently cost $8.50 each and have a maximum value of $999.99.
Electronic payments, Interac e-Transfers and wire transfers may also be suitable depending on the size and purpose of the payment.
| Certified Cheque | Bank Draft | Canada Post Money Order | |
|---|---|---|---|
| Issued by | Account holder, then certified by financial institution | Financial institution | Canada Post |
| Typical fee | About $10 to $20 | Commonly $9.95 | $8.50 |
| Maximum amount | Depends on financial institution | Depends on financial institution | $999.99 |
| Common today | Less common | Common | Available through Canada Post |
- Issued by
- Account holder, then certified by financial institution
- Typical fee
- About $10 to $20
- Maximum amount
- Depends on financial institution
- Common today
- Less common
- Issued by
- Financial institution
- Typical fee
- Commonly $9.95
- Maximum amount
- Depends on financial institution
- Common today
- Common
- Issued by
- Canada Post
- Typical fee
- $8.50
- Maximum amount
- $999.99
- Common today
- Available through Canada Post
Certified cheques are excluded from the normal six-month stale-date rule that applies to ordinary cheques in Canada. However, it is still a good idea to deposit a certified cheque promptly and check with your financial institution if the cheque is particularly old.
Cancellation procedures depend on the issuing financial institution. Contact the bank or credit union that certified the cheque. The original cheque may need to be returned before the reserved funds can be released. If the certified cheque was lost, stolen, or destroyed, there may be a waiting period before the held funds can be released.
A certified cheque can generally be deposited like another cheque. Depending on the financial institution and the cheque, you may be able to deposit it at a branch, ATM or through mobile cheque deposit.
A hold may still be placed on the funds while the financial institution processes or verifies the cheque.
Disclaimer:
- Any analysis or commentary reflects the opinions of WOWA.ca analysts and should not be considered financial advice. Please consult a licensed professional before making any decisions.
- The calculators and content on this page are for general information only. WOWA® does not guarantee the accuracy and is not responsible for any consequences of using the calculator.
- Financial institutions and brokerages may compensate us for connecting customers to them through payments for advertisements, clicks, and leads.
- Interest rates are sourced from financial institutions' websites or provided to us directly. Real estate data is sourced from the Canadian Real Estate Association (CREA) and regional boards' websites and documents.